Author: finalboss

  • Japan’s Games Market: Platform Mix and Global Publisher Exposure

    Japan’s domestic games market reached ¥2.396 trillion in 2024, up 3.4%, with mobile driving most of the increase. Publisher overseas-sales ratios reveal a separate dimension of scale, but their different accounting scopes prevent them from being combined into a national export ratio.

    Japan’s PC-game revenue more than doubled between 2020 and 2024 while console revenue declined. For publishers assessing domestic demand and international distribution, that divergence makes platform mix — not corporate nationality — the starting point for analyzing the video game industry in Japan.

    The analytical framework separates domestic market demand, company-level overseas exposure and control over intellectual property (IP). Each measures a different source of resilience or dependency. A Japanese publisher can generate most of its business overseas, while a growing Japanese market can support games developed outside Japan.

    1. Domestic market weight starts with comparable revenue categories

    CESA’s 2025 industry-report preview places Japan’s domestic games market at ¥2.396 trillion in calendar 2024, an increase of 3.4% over the previous year. Mobile accounted for most of that growth. The non-mobile market totaled ¥648 billion, comprising ¥383 billion in console revenue and ¥265 billion in PC revenue.

    Market measure20202024Analytical significance
    Total domestic games market—¥2.396 trillionMeasures domestic market scale, not worldwide sales by Japanese companies.
    Console games¥395 billion¥383 billionThe segment declined across the comparison period.
    PC games¥122 billion¥265 billionRevenue more than doubled, making PC the principal growth segment within non-mobile games.

    The first analytical finding is that aggregate growth conceals different platform trajectories. A publisher concentrated in domestic console releases faces a different demand environment from a mobile live-service operator or a company expanding its PC catalog. The national growth rate is not a common growth assumption for all three.

    Scope control also prevents double counting. Domestic market revenue, consumer spending, platform-holder sales and publisher revenue occupy different layers of the value chain. Adding Nintendo’s consolidated sales to Japan’s domestic market total would combine worldwide corporate activity with a geographic market measure. Store fees, taxes, royalties and intercompany transactions further complicate reconciliation.

    2. Mobile growth and audience growth are different signals

    Mobile is the largest structural component of Japan’s domestic games economy. Its commercial model relies heavily on recurring in-app purchases, time-limited events, collectible characters and gacha-style systems, in which players spend for randomized rewards. For these businesses, franchise appeal, content cadence and conversion into spending can matter as much as audience expansion.

    CESA’s 2024 participation figures show mobile users declining 1.8% and console users declining 0.7%, while PC users increased 0.5%. Mobile revenue growth therefore coincided with falling mobile participation. Those aggregate trends do not identify whether the revenue change came from payer conversion, spending per payer or the mix of games generating revenue.

    A separate Sensor Tower estimate cited by IMARC puts Japanese mobile-game in-app-purchase revenue at approximately US$11 billion for the 12 months ending July 2025. That figure measures mobile purchases in a different currency and reporting period from CESA’s calendar-2024 all-platform total. It provides another measure of mobile monetization scale, not a directly comparable component of the yen-denominated market total.

    At title level, the relevant diagnostic series include paying-user share, average revenue per user (ARPU), spending per payer and retention by acquisition cohort — users grouped by when they were acquired. D1, D7 and D30 retention describe the share of a defined cohort active on the corresponding day after acquisition. Comparing retention and spending around events or character releases helps assess whether spending peaks accompany sustained engagement; national revenue growth supplies no title-level retention or acquisition-cost benchmark.

    3. Handheld use and PC distribution complicate the console comparison

    Nintendo Switch combines portable and television-based play within one platform family. A portable-versus-stationary revenue split therefore cannot be inferred from the ¥383 billion console total. Treating all Switch activity as either traditional home-console demand or a separate handheld market would impose a distinction that the hardware itself crosses.

    This matters when comparing Japan with Western markets. A useful comparison separates device usage, software purchasing and publisher business models rather than treating each region as a single console market. Nintendo’s integrated hardware-and-software economics are also different from those of a software-only publisher, irrespective of headquarters location.

    PC growth introduces another distinction: Japanese demand for PC games is not the same measure as overseas demand for Japanese PC games. Steam is a distribution route for Japanese publishers, but the increase from ¥122 billion to ¥265 billion does not isolate Steam’s contribution or identify the nationality of the games purchased.

    Cross-platform distribution can spread dependence across storefronts and device ecosystems while adding platform-specific adaptation, support and release-management work. It also leaves franchise concentration intact when the same small set of properties supplies revenue across every platform.

    4. Overseas-sales ratios measure different publisher businesses

    Japanese publishers’ overseas ratios demonstrate substantial international reach, but they measure different businesses. Revenue shares and unit shares answer different questions; consolidated company sales and individual segment sales have different boundaries. FY2025.3 denotes the fiscal year ended March 2025, while interim presentations cover their stated reporting periods rather than the full year.

    Company and disclosureOverseas indicatorWhat it measuresMain limitation
    Nintendo, February 2025 financial-results material76.5% of sales outside JapanGeographic exposure across Nintendo’s consolidated business.Includes an integrated hardware-and-software model, not game software exports alone.
    Bandai Namco, FY2025.3 Network Content45% overseas sales ratioOverseas exposure within a business generating ¥195.1 billion in sales.Applies to Network Content, not the entire group or all its game businesses.
    Capcom, third-quarter FY2025.3 presentation82.2% overseas game-unit shareGeographic distribution of game units in the displayed reporting period.Measures units rather than revenue and varies with release mix and reporting period.

    The central distinction is between overseas business and a national export statistic. Nintendo’s ratio cannot be applied to all Japanese publishers, and Capcom’s unit share cannot be converted into a revenue share without regional pricing and product-mix information. None of these disclosures supplies a consolidated percentage of Japan’s entire games industry exported.

    Bandai Namco illustrates how the denominator changes the result. Its FY2025.3 consolidated geographic breakdown assigns 69.8% of sales to Japan and 30.2% outside Japan. That group includes toys, hobby products and other businesses. The 45% overseas ratio for Network Content is consequently the more directly relevant measure for that digital-game business, rather than evidence that one geographic figure supersedes the other.

    5. Integrated franchises diversify revenue but retain shared dependencies

    Nintendo controls hardware platforms, first-party software, digital distribution and major proprietary franchises. Bandai Namco links games with animation, toys, character goods and other IP businesses. These structures capture value across more activities than a publishing model limited to distributing third-party software.

    The resulting resilience is conditional. A franchise can generate revenue through premium games, downloadable content, mobile services, merchandise and licensing, reducing dependence on a single release format. Those channels can still depend on the same characters, rights agreements and audience sentiment. Channel diversification does not automatically create franchise diversification.

    Rights ownership is therefore a franchise-level variable. Corporate identity alone does not establish control over every character, adaptation or regional licensing arrangement. The relevant comparison concerns the rights retained, the production functions controlled and the revenue channels consolidated — not a blanket distinction between Japanese and Western publishers.

    6. Platform rules and territorial access remain separate risk layers

    Japan’s mobile model carries exposure to scrutiny of randomized rewards, including Consumer Affairs Agency concerns involving minors. That scrutiny is distinct from a blanket prohibition on gacha: recurring in-app purchases and randomized acquisition mechanics remained operational in the reported period.

    Apple and Google payment rules, store fees, age requirements and platform terms affect mobile economics independently of consumer demand. Overseas distribution adds territory-specific constraints. Japan’s treatment of randomized purchases does not establish access under China’s separate publishing and disclosure regime.

    For cross-border analysis, revenue by customer geography describes exposure, while storefront availability, local publishing arrangements and applicable content rules describe access. A high overseas sales ratio demonstrates international demand; it does not establish equal access to every market or independence from a particular platform.

    7. Operational indicators and failure modes

    • Domestic demand: Mobile payer conversion, event revenue and cohort retention help distinguish monetization gains from audience expansion. Aggregate growth can conceal declining participation.
    • Platform migration: Domestic PC revenue, overseas PC sales and handheld-capable console activity are separate series. Combining them can misidentify where demand is moving.
    • Export concentration: Overseas revenue by territory, franchise and distribution partner reveals dependencies that a single company-wide percentage conceals. Unit shares do not substitute for revenue shares.
    • Rights and access: IP ownership, storefront terms and regional publishing requirements determine how much control remains with the publisher. Additional channels can diversify distribution while preserving exposure to the same franchise or rights holder.

    Conclusion

    Japan’s mobile-led market growth and expanding PC revenue point to different domestic opportunities, not a uniform growth outlook across platforms. Japanese publishers’ international scale adds a separate dimension, shaped by franchise ownership, distribution access and the businesses included in each disclosure. Market forecasts are most useful when domestic demand, overseas exposure and rights control remain distinct rather than being compressed into one industry growth or export assumption.
  • Game Publishing Deals: How Advances, Royalties and IP Rights Interact

    A game publishing agreement separates project funding, cost recovery, revenue sharing and control of intellectual property. Its economic effect depends on how those provisions interact, especially when sales disappoint, costs expand or the publishing relationship ends.

    A studio can finish a game, retain its intellectual property and receive no sales royalties while its publisher continues distributing it. That outcome can follow directly from an exclusive publishing license, an outstanding recoupment balance and a contract that recovers costs before paying the developer.

    In the video game publishing industry, the headline advance and royalty percentage describe only part of a deal. A useful assessment connects four separate mechanisms: when development funding arrives, which revenue repays which costs, how subsequent receipts are shared, and when publishing rights become available to the developer again.

    • Funding exposure: milestone acceptance and payment conditions determine whether the advance supports production when expenditure occurs.
    • Recoupment exposure: the recovery base, permitted costs and cross-collateralization determine how long developer royalties remain unavailable.
    • Control exposure: IP ownership, exclusivity and derivative-work rights determine which activities remain within the studio’s control.
    • Exit exposure: termination payments, surviving licenses and access to operational assets determine whether rights reversion is usable in practice.

    The starting point: the publisher’s actual service package

    A publisher may finance development, supervise production, handle platform submissions, commission localization, fund marketing, distribute the game and operate customer support. Those activities create different delivery obligations and potentially different recoupable costs. “Publishing services” is therefore too broad a category to explain the economics on its own.

    The analytical distinction is between services the publisher commits to provide, services it may provide at its discretion, and services charged against game revenue. A marketing commitment and permission to incur recoupable marketing expenditure are not equivalent: one establishes an obligation to act, while the other establishes authority to spend.

    Control and cost responsibility also interact. A publisher with discretion over localization, ports or promotion can increase the recovery balance without changing the headline advance. Approval thresholds, spending caps and the treatment of unused budgets reveal how much of that balance remains within either party’s control.

    Advances: production funding is not the same as royalty income

    A recoupable advance is paid against the developer’s future royalties. It provides cash before those royalties become payable, but it is not an additional sales bonus. Its loan-like economic effect does not, by itself, establish an obligation to repay the publisher from the studio’s other funds; cash repayment depends on the agreement, including its termination provisions.

    Advances commonly arrive in milestone payments rather than as one unrestricted transfer. Milestones can attach to signing, prototype approval, production deliveries, platform submission, certification, launch or post-launch work. Acceptance criteria matter because delivery and payment can occur at different times, particularly where approval depends on publisher discretion.

    The funding assessment connects the payment schedule with the development budget and acceptance process. It distinguishes an incomplete delivery from a delayed review, identifies the treatment of disputed milestones, and establishes whether production overruns create additional recoupable costs. An advance can fund only part of production even when its full amount is recoverable from royalties.

    The publisher’s exposure is the funding and approved expenditure that the game fails to recover. The developer’s exposure includes gaps between expenditure and milestone receipts, delayed royalties and any contractual repayment duties. These exposures differ even when both parties describe the arrangement as fully recoupable.

    Recoupment: identifying the revenue stream that repays the costs

    A conventional waterfall starts with receipts, applies permitted deductions, recovers defined costs and distributes the remaining revenue under the royalty schedule. The critical distinction is whether recovery uses all qualifying receipts before a split, only the developer’s allocated royalty stream, or a structure that also pays the developer before full recovery.

    Revenue mechanismEconomic treatmentPrincipal trade-off
    Publisher-priority recovery before sharingDefined receipts repay the advance and other eligible costs before the post-recoupment split applies.The publisher receives priority; the developer may receive no sales royalties until the recovery threshold is reached.
    Recovery from the developer’s royalty shareThe developer’s allocated royalties are withheld and credited against the recoupment balance.“Fully recoupable” does not mean all game receipts reduce the balance; recovery can take longer than the headline sales performance suggests.
    First-dollar participationThe developer receives an agreed share before all eligible costs have been recovered.Earlier developer cash flow reduces the publisher’s recovery priority on the receipts shared.

    These mechanisms can coexist within different phases of one agreement. The operative waterfall, rather than its label, determines the cash outcome.

    “Net revenue” is equally consequential. Platform fees, taxes, refunds, chargebacks, payment processing and distribution charges may reduce receipts before royalties are calculated. Marketing, localization, porting, support and development expenditure may also be deductible or recoupable, depending on the contract. Consumer spending, platform receipts and publisher receipts are different accounting bases.

    A revealing reconciliation separates deductions used to calculate net revenue from costs posted to the recoupment balance. A platform fee already removed before the publisher receives payment is not an additional cash expense merely because it also appears on a statement. Tracing each charge through both calculations exposes duplicate treatment and explains why strong sales may not produce a developer payment.

    Cross-collateralization changes the boundary of the calculation. Revenue from one game can repay another game’s advance, an earlier agreement or expenditure associated with DLC, ports or other territories if the contract permits it. This reduces title-specific downside for the publisher but can prevent a successful release from generating developer royalties because an unrelated balance remains outstanding.

    Royalty splits: the percentage follows the accounting definition

    Mad Mushroom’s public 2024 developer-publisher agreement specifies a royalty allocation of 70% of net revenue to the developer and 30% to the publisher. That is a documented contractual example, not an industry benchmark. Another agreement with the same percentages can produce a different payment if its revenue definition, deductions or recoupment order differ.

    The revenue schedule also determines how different commercial routes participate. Digital sales, physical distribution, DLC, virtual goods, advertising, bundles, subscriptions and cloud distribution can have different royalty treatments. A bundle or subscription payment introduces an attribution question: how much of a combined payment belongs to this game before the royalty calculation begins?

    Pricing authority affects the same base. Discounts, regional pricing and subscription inclusion can increase distribution while reducing receipts per transaction. The relevant criteria are the publisher’s pricing discretion, any approval conditions and the allocation method for payments that do not attach to an individual sale.

    Accounting makes these provisions testable. The Mad Mushroom agreement provides for royalty statements within 60 days after the end of each month in which the publisher receives gross revenue. A statement deadline is distinct from the payment deadline, and neither substitutes for access to the underlying records.

    A recoupment reconciliation connects the opening balance, newly eligible costs, recovery credits and closing balance. Supporting records connect those entries to platform receipts, refunds, expenditure and revenue allocations. Audit coverage then determines whether the developer can examine those records, within what period, and under which confidentiality and frequency limits. A nominal audit right has limited operational value if it excludes the records that explain the deductions.

    IP ownership and publishing authority are separate questions

    Developer ownership does not imply unrestricted developer control during the publishing term. An exclusive license can leave the studio owning the game while preventing it from distributing the same product independently or appointing another publisher within the licensed scope.

    The Fig Publishing amended license agreement separates ownership of the licensed game and developer brand features from the licensee’s own brand features. A different Fig revenue-sharing agreement dated 2022 grants broad distribution permissions, including reproduction, modification, hosting, transmission and sublicensing for approved sales. Together, these structures illustrate why ownership and exploitation authority require separate analysis.

    The rights map distinguishes game content, characters, trademarks and source code from pre-existing tools and technology. It also separates publisher-created advertising and technical materials from developer-created assets. A studio may retain its game while still needing a continuing license to use publisher-owned materials after termination.

    Sequel, remake, remaster, adaptation, merchandising and derivative-work rights introduce additional boundaries. Broad grants covering modifications, future versions or all development materials can extend beyond the initial release. An assignment transfers the specified ownership rights; a license grants permissions whose duration and scope depend on its terms. A perpetual license may therefore constrain future activity even without an ownership transfer.

    Third-party middleware, music, fonts and outsourced assets place another limit on the grant. The developer cannot convey permissions that its own licenses do not contain. Restrictions on sublicensing, modification or transfer can affect ports, replacement developers and the later handover of the game.

    Platform and compliance duties can expand both costs and liability

    For a publishing arrangement spanning PC, PlayStation 5, Xbox Series X|S or Nintendo Switch, platform scope is an operational allocation as well as a rights grant. Submission responsibility, certification work, porting expenditure and update obligations affect delivery acceptance and recoupment. A release-window trigger tied to certification has different dependencies from one tied to final delivery or publisher acceptance.

    Territorial publishing rights do not themselves establish lawful market access. Ratings, consumer rules, privacy duties and platform requirements remain separate constraints. The contract’s allocation of those responsibilities determines who performs the work, who bears a failure and whether remediation adds to the recoverable balance.

    Generative AI adds a chain-of-title and compliance dimension. Training material and generated outputs create IP infringement exposure; ownership treatment differs across jurisdictions; and prompts can contain protected or personal information. Written AI-use policies increasingly form part of publishing and other commercial requirements, alongside provisions in contractor and talent agreements.

    For EU-facing services, the applicable analysis can also include AI Act transparency duties, in-game currency pricing principles, national gambling-law exposure and user-generated-content obligations. Article 28 of the Digital Services Act requires online platforms accessible to minors to take measures ensuring high privacy, safety and security; an 18+ statement in the terms alone does not remove that scope. This is not a blanket classification of every game as an online platform.

    These duties connect directly to publishing economics when moderation, disclosures, asset replacement or continuing support are publisher-controlled services charged to the game. They also affect reversion if the developer later assumes operation without receiving the systems, records or permissions needed to continue those functions.

    Rights reversion: separating the trigger, the price and the handover

    Rights reversion restores specified publishing or exploitation rights after a contractual event. Possible triggers include non-release, abandonment, expiry, breach or insolvency. Weak sales do not automatically trigger reversion, and delisting or discontinued support matters only to the extent covered by the agreement.

    The trigger analysis turns on an identifiable event and a measurable period. A release obligation measured from signing differs from one measured from final delivery, certification or acceptance. Publisher discretion over the starting event can affect whether the clock begins. Territory-specific or platform-specific rights may also remain dormant even while the publisher actively exploits the game elsewhere.

    The economics after termination form a separate test. The Mad Mushroom 2024 agreement includes specified termination provisions involving repayment of an unrecouped advance and recoupable costs, together with payment of the fair market value of granted licenses. It also contains a specified publisher-termination scenario with a reduced 40% developer royalty after all recoupable costs have been recovered. Recoupment completion therefore does not necessarily activate the agreement’s highest developer share.

    A repayment or license-buyout requirement can make an available exit financially difficult to exercise. Valuation methodology, the treatment of outstanding costs and the distinction between publisher default and developer default all influence the result. Termination, repayment and reversion are related events, not interchangeable terms.

    The final test concerns operational continuity. Legal rights alone do not provide access to builds, store infrastructure or the materials needed to maintain the game. The handover assessment covers:

    • Production assets: source code, build tools, documentation, localization files and the permissions needed to use them.
    • Distribution assets: platform accounts, store listings, submission access and any platform-dependent transfer conditions.
    • Customer operations: support obligations, community channels and customer-data handling consistent with applicable privacy duties.
    • Residual publisher rights: surviving sublicenses, physical-inventory sell-off, continuing customer service and accounting for later receipts.

    A defined wind-down allows the publisher to complete approved obligations without leaving exploitation rights indefinitely unresolved. The practical result is visible in the handover package: whether the studio can maintain the existing game, distribute it through permitted routes and use the relevant assets after the publishing license ends.

  • Why Live-Service Games Shut Down: An Operating Risk Framework

    A live-service game is a continuing operating model built around sustained engagement, ongoing content and recurring revenue. Shutdown risk rises when the retained audience cannot support the permanent team, production pipeline and operational obligations behind that service.

    Sony launched Concord on PlayStation 5 and PC on August 23, 2024, and took its servers offline on September 6. That two-week service life ended before a seasonal content calendar could demonstrate lasting value. It illustrates the first hurdle in live-service economics: establishing an audience large and durable enough to justify continuing operations.

    • Revenue concentration: a large free-to-play audience can generate insufficient revenue when too few active players purchase regularly.
    • Population density: total player counts can conceal weak matchmaking across regions, platforms, skill bands and modes.
    • Production capacity: seasonal content competes with bug fixes, exploit response and maintenance for the same development resources.
    • Exit classification: cancellation, reduced support and server shutdown are different outcomes, with different consequences for players and publishers.

    What is a live-service game?

    A live-service game is designed to receive continuing content, updates, events, operational support and monetisation after launch. Live service describes an operating model, not a genre: it can underpin an MMO, competitive shooter, extraction game, sports title or predominantly single-player experience.

    The games-as-a-service model extends the commercial relationship beyond the initial sale. Revenue can come from subscriptions, expansions, battle passes, cosmetics, virtual currency or other recurring purchases. The operating cycle connects player acquisition, initial engagement, retention and spending; its viability depends on repeated participation rather than launch sales alone.

    Neither an internet connection nor multiplayer functionality is sufficient to make a game a live service. A traditional multiplayer release can receive patches and maintain servers without sustaining a seasonal production organisation. Conversely, a live service need not be free-to-play.

    Commercial structureExampleRevenue relationshipPrincipal operating tension
    Free-to-play serviceFortniteFree access, with optional recurring purchases such as cosmetics and passes.A minority of purchasers supports a much larger active population and continuing content production.
    Premium live serviceHelldivers 2Paid entry alongside optional purchases and ongoing content.Upfront sales support launch economics, but the entry price can restrict audience growth.
    Subscription-led serviceFinal Fantasy XIVSubscriptions and expansions sustain an ongoing paid relationship.Recurring payment creates a continuing expectation of content, reliability and support.

    The cost base continues after launch

    A live-service launch begins an operating commitment. Engineering, design, art, production and quality assurance remain necessary, alongside community management, data analysis, customer support, moderation, anti-cheat and infrastructure operations. The organisation is maintaining a product while simultaneously building its next release.

    Seasonal production creates overlapping workloads. While one season is live, another requires implementation and testing, and later content requires planning. Maps, characters, cosmetics, balance changes and promotional assets share capacity with crash fixes, exploit investigations and account problems. A roadmap can so exceed sustainable capacity even when each individual addition looks manageable.

    Server hosting is only one component of the operating bill. Authentication, databases, bandwidth, matchmaking, telemetry, payment processing, fraud prevention and backups also remain active. Infrastructure usage can vary with demand, while core staffing and content-production costs are less flexible. A shrinking audience does not automatically produce a proportionate reduction in costs.

    Marketing also becomes recurring. Seasonal launches, collaborations and creator campaigns compete for attention after the original release campaign ends. Acquisition spending can increase activity while worsening operating economics if the additional players generate less contribution than their acquisition and servicing costs.

    The continuation calculation compares net receipts with the future cost of content, personnel, infrastructure, support and marketing. Historical development spending affects the project’s overall economics, but continued operation depends on what the service can generate from that point onward — and what maintaining it prevents the studio from producing elsewhere.

    Four tests of live-service resilience

    1. Audience density, not just launch reach

    Registered accounts, launch sales, monthly active users and concurrent players describe different populations. MAU counts unique monthly active users. CCU measures simultaneous players. A Steam concurrency chart captures activity on that storefront, not the entire cross-platform audience.

    For a matchmaking-dependent service, the decisive population is often narrower still: players available in a particular region, mode, skill range and input pool at the same time. A substantial global audience can coexist with long queues or poor match quality in individual segments. Cross-play can improve density, but adds account, entitlement, technical and enforcement complexity.

    This creates a reinforcing failure mode. Lower population weakens matchmaking; weaker matches reduce engagement; declining engagement further reduces population. The mechanism can impair a service before its headline audience reaches an obviously small number.

    2. Cohort retention, not seasonal spikes

    Day-one, day-seven and day-30 retention — D1, D7 and D30 — track whether members of an acquisition cohort remain active at defined intervals after starting. Cohorts distinguish durable engagement from a launch surge or promotional event. Comparisons depend on consistent measurement conventions, acquisition channels, platforms and audience characteristics.

    DAU, or daily active users, describes daily reach. The DAU/MAU ratio approximates activity frequency within the monthly audience, but does not identify which cohorts persist or whether purchases cover costs. An expansion can lift both metrics temporarily while the underlying audience continues to churn.

    Genre also changes interpretation. A competitive service organised around frequent sessions has a different engagement pattern from an MMO expansion cycle. The useful distinction is between a predictable content-driven lull and erosion that successive updates fail to reverse.

    3. Payer conversion and net contribution, not gross spending

    Free-to-play services usually monetise a minority of their active players. Revenue therefore depends on both payer penetration — the share making purchases — and spending per purchaser. High average revenue per paying user, or ARPPU, can conceal a narrow payer base.

    Average revenue per user, or ARPU, also needs a defined denominator and reporting period. Revenue per monthly active user is not interchangeable with revenue per registered account or lifetime install. Consistent definitions expose whether revenue growth comes from broader conversion, higher spending among existing purchasers or a temporary event.

    Gross player spending is not publisher contribution. Storefront fees, payment costs, taxes and refunds reduce receipts, with terms varying by platform, product and agreement. Lifetime value, or LTV, is meaningful in acquisition analysis only when its revenue scope and cost deductions are explicit. Gross lifetime receipts do not describe the amount available to fund content and operations.

    4. Production capacity, not promised cadence

    Arc Raiders provides a concrete capacity example. Embark moved from planned monthly updates to larger twice-yearly content additions after the team became exhausted. Executive producer Aleksander Grøndal described a team repeatedly overshooting its capacity, with bug fixes, exploits and maintenance consuming much of its time.

    The operational discovery was that scheduled content did not represent the whole workload. Maintaining the existing service absorbed capacity that the original roadmap had effectively allocated to new production. Embark reworked its long-term plan to protect staff from burnout and described improved iteration after the change.

    A slower cadence can reduce production pressure and create more space for testing. It also creates longer intervals between major engagement events. Its effect depends on whether the existing game supports sustained play, rather than on update frequency in isolation.

    Why the early operating period is vulnerable

    The first 12-24 months expose whether launch acquisition becomes durable engagement and whether repeated content releases are economically sustainable. Initial purchases can obscure weak recurring spending. A successful launch campaign can obscure churn. A heavily prepared first season can obscure a production pipeline that cannot maintain its pace.

    Established services also possess advantages that a competent new game does not immediately replicate: friendship groups, accumulated progression, purchased cosmetics, familiar mechanics and extensive content libraries. A new entrant competes against those relationships as well as against the incumbent’s current gameplay.

    That makes differentiation a commercial requirement, not simply a creative distinction. A polished game can struggle when its intended audience has little reason to move from an established service. Launch crashes, cheating, weak matchmaking or an unpopular economy can make that transition still harder.

    A market-wide failure rate is a separate calculation from a list of prominent closures. It needs a complete launch cohort, a defined observation period and consistent treatment of server shutdowns and support withdrawal. Projects cancelled before release belong outside a launch-survival denominator.

    Public closure cases reveal different failure modes

    Publisher announcements establish when service or development ended and what happened to access. The cases below separate short-lived launches from portfolio cancellations and the withdrawal of official support.

    Game and operatorDocumented outcomeAnalytical significance
    Concord — Sony / FirewalkLaunched August 23, 2024; servers closed September 6, 2024. Sony subsequently closed Firewalk.The service ended before a sustained seasonal cycle could develop. Launch viability and long-term content sustainability are separate tests.
    Rumbleverse — Epic Games / Iron GalaxyLaunched in August 2022; closed February 28, 2023, with purchases eligible for refunds.Free access did not protect the service from an early exit. Refund handling became part of the closure process.
    Babylon’s Fall — Square Enix / PlatinumGamesLaunched in March 2022; service ended February 27, 2023. Square Enix cited difficulty attracting and retaining players.Acquisition and retention failed to sustain continued service through its first year.
    The Last of Us Online — Naughty Dog / SonyDevelopment was cancelled in December 2023, before launch.Naughty Dog said ongoing support would require focusing almost exclusively on post-launch content, severely affecting future single-player development.
    Marvel’s Avengers — Crystal DynamicsOfficial support ended September 30, 2023; existing owners retained access to the game.The end of content and support did not mean immediate loss of playability.
    Knockout City — Velan StudiosGlobal service ended June 6, 2023, after more than two years. A private PC server version enabled community-hosted play.Publisher-operated service ended, while a separate technical route preserved community play.

    Naughty Dog’s decision exposes a studio-level constraint that player metrics alone cannot capture. A permanent service organisation can displace other production even before its prospective revenue is tested. Sony’s January 2025 cancellations of live-service projects associated with Bend Studio and Bluepoint Games similarly concerned portfolio allocation, rather than the shutdown of launched games.

    Public closure announcements generally do not contain complete payer-conversion data, operating costs or product contribution. A closure can coexist with an active community: the relevant decision may concern the expected economics of continued operation or the competing demands on studio capacity.

    Platform and regional constraints change the operating equation

    PlayStation, Xbox and Nintendo releases face platform-holder technical and policy requirements. Certification can affect patch timing and emergency-fix coordination. Cross-play and cross-progression add dependencies involving compatible versions, account linking, inventories, virtual currencies and purchase entitlements. Wider distribution increases potential reach, but also increases the number of systems that must remain compatible.

    On mobile, Apple’s App Store and Google Play impose review, payment, privacy and age-rating requirements. Regional rules can alter the monetisation design itself. China requires probability disclosures for many randomised virtual-item systems, while other jurisdictions apply additional consumer-protection or gambling-related scrutiny.

    Nominal global reach is therefore different from a single, interchangeable market. Country-specific product restrictions, payment flows and data obligations can require different service configurations. Regional availability and matchmaking segmentation also affect how much of the overall audience contributes to a healthy local player pool.

    Persistent accounts create continuing responsibilities for privacy notices, access requests, retention and deletion. Competitive and social systems add moderation, reporting and enforcement workloads. These obligations remain part of the operating model during quieter content periods; reducing the roadmap does not remove them.

    Service withdrawal is a product-design issue as well as a closure decision

    Ending active development, closing a store, delisting a game and disabling authentication are separate actions. Their consequences depend on the architecture. A game that retains local, peer-to-peer or community-hosted functionality can remain usable after official operations end. A game dependent on publisher authentication or dedicated servers may become inaccessible.

    The observed options carry different trade-offs. Embark’s cadence reduction preserves active development while reducing production pressure. Marvel’s Avengers retained playability without continuing official support. Knockout City transferred part of the preservation burden to community hosts. None of these outcomes is equivalent to maintaining the original service unchanged.

    Closure also creates work: access notices, purchase eligibility decisions, refunds where applicable, data handling and customer support. The loss of purchased items, progression or social spaces can weaken trust in later launches from the same publisher. For market analysis, service resilience therefore includes both the capacity to sustain operations and the technical consequences when those operations end.

  • UFC-Que Choisir attaque Ubisoft : le géant français priverait les joueurs de ce jeu qu’ils ont pourtant acheté

    UFC-Que Choisir attaque Ubisoft : le géant français priverait les joueurs de ce jeu qu’ils ont pourtant acheté

    Key signals

    • UFC-Que Choisir has sued Ubisoft in Créteil over The Crew’s March 2024 server shutdown, arguing paying customers lost all access to a purchased game.
    • The case targets revocable-license clauses and late notice of shutdowns, challenging industry-standard EULAs across PC, PlayStation, and Xbox stores.
    • A ruling against Ubisoft could force new guarantees for offline modes, longer support horizons, or clearer “expiry” disclosures for server-dependent titles.
    • Backed by the Stop Killing Games campaign and over one million signatures, the action lands as EU policymakers scrutinize digital ownership and game preservation.
    • A Ubisoft win would reinforce the status quo license model, aligning with the 2024 French ruling favoring Valve on digital resale restrictions.

    What changed: From server shutdown to test case

    French consumer association UFC-Que Choisir has filed a lawsuit against Ubisoft at the Tribunal Judiciaire de Créteil (Val-de-Marne) over the permanent shutdown of servers for The Crew, the 2014 open-world racing game released on PC, PlayStation, and Xbox platforms. Ubisoft switched off the game’s servers in March 2024, which, due to its server-dependent design, rendered the title completely unusable, including for previously available solo modes.

    UFC-Que Choisir argues that consumers who paid for The Crew were never clearly informed that access was time-limited or that use was strictly conditional on Ubisoft’s continued operation of online services. The suit challenges Ubisoft’s contractual framing of purchases as revocable licenses rather than ownership of a durable product, and seeks removal of what the association characterizes as abusive clauses in Ubisoft’s terms of use.

    The case is explicitly framed as a collective-interest action rather than a narrow refund dispute. The Crew functions as the test example for a wider question: does the purchase of a digital game, via disc or download, entail a right of use that cannot be unilaterally extinguished by the publisher once servers are turned off?

    The legal theory: Revocable licenses vs. consumer rights

    At the core of the complaint is the clash between standard industry EULAs and European consumer protection concepts. Publishers and platforms such as Ubisoft Connect, Steam, PlayStation Store, and Xbox storefronts typically present access as a non-transferable, revocable license, reserving broad rights to suspend services and remove content. UFC-Que Choisir considers this structure a “denial of ownership” for consumers who believed they were buying enduring access to a product.

    The association highlights several contract elements it views as abusive:

    • Clauses allowing Ubisoft to terminate access without guaranteeing any offline fallback mode.
    • Design choices that tie even solo play to online services that can be cut at publisher discretion.
    • Exclusions of reimbursement for unused balances in digital wallets if related services are withdrawn.
    • Lack of explicit, upfront disclosure that access to the game would cease entirely at a given date.

    UFC-Que Choisir also alleges misleading commercial practices: marketing and store pages, it argues, led buyers to believe they enjoyed a right of use not conditioned on the continued operation of online servers, whereas in reality the product was fully dependent on backend infrastructure with no guaranteed lifespan.

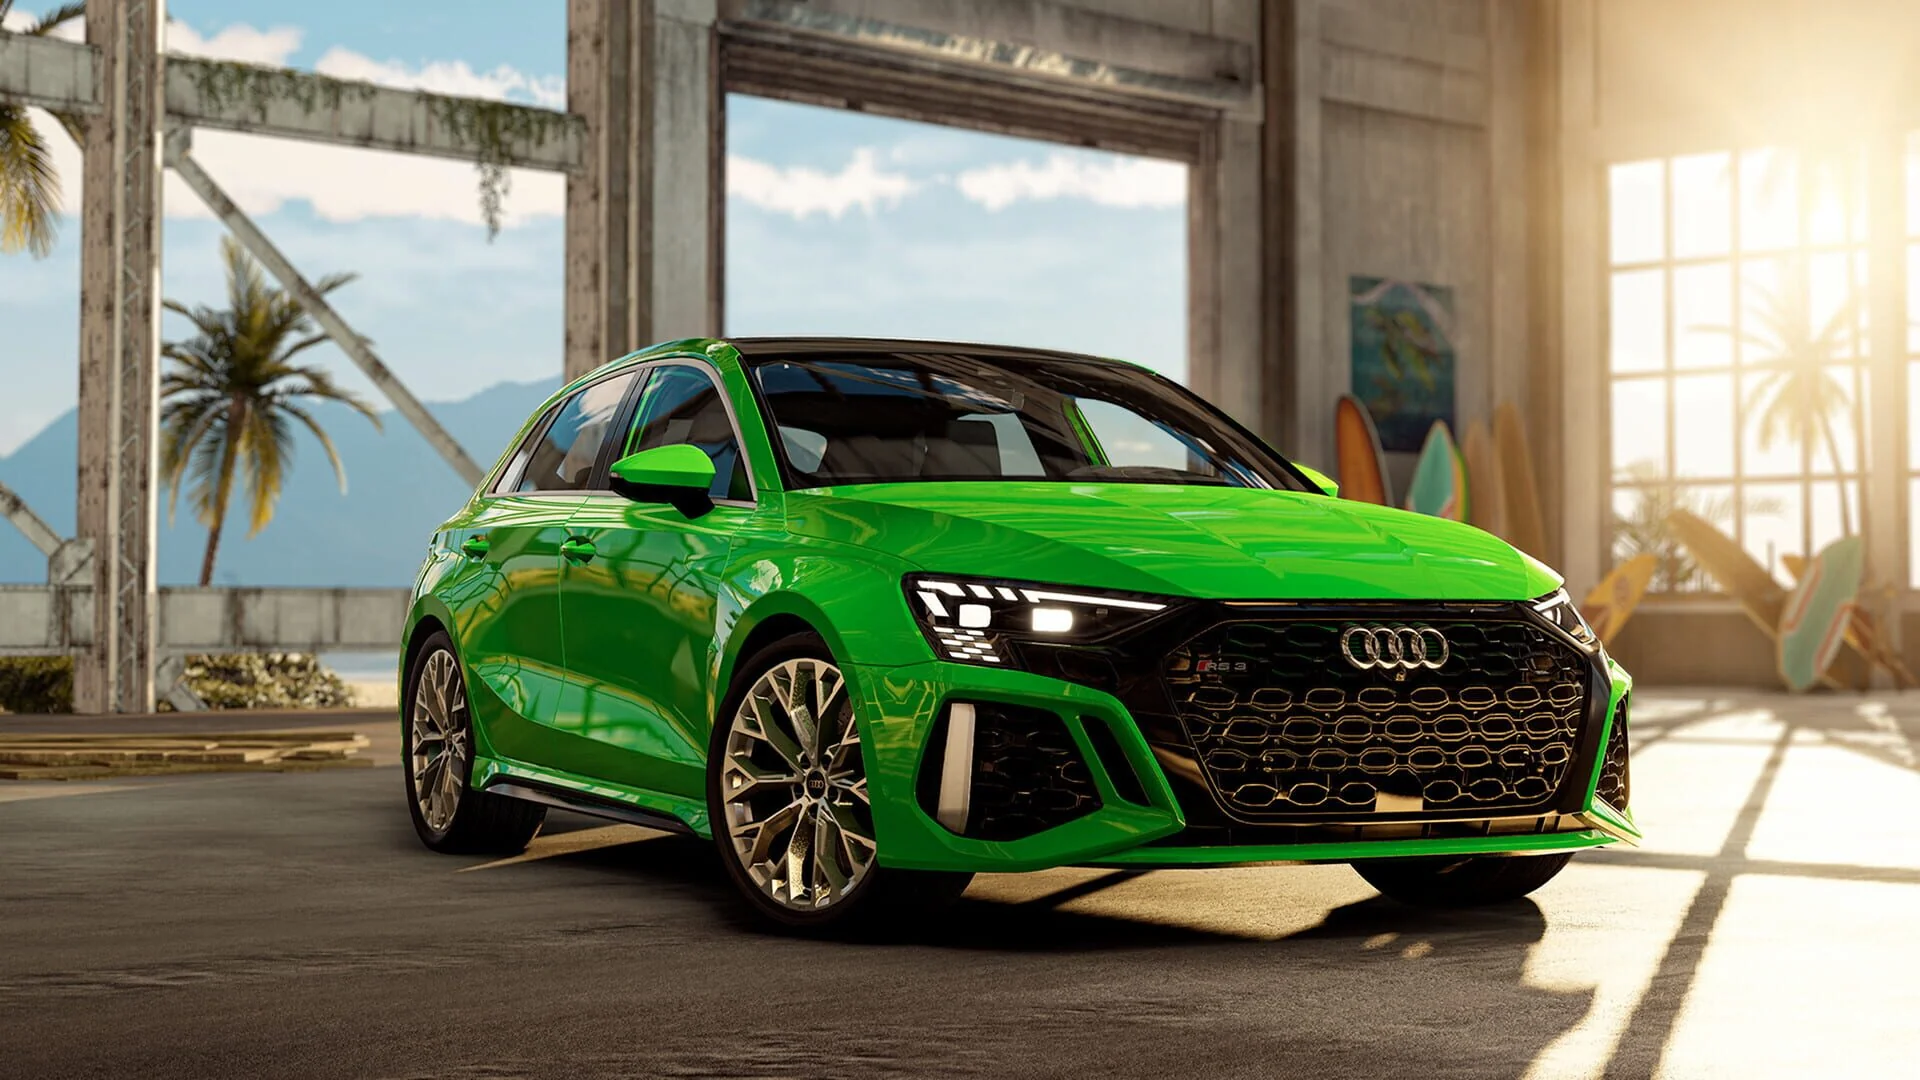
    Screenshot from The Crew Motorfest: Audi Double Car Pack
    Screenshot from The Crew Motorfest: Audi Double Car Pack

    European context: Stop Killing Games and the Valve precedent

    The lawsuit does not occur in isolation. It is backed by the Stop Killing Games (SKG) initiative, which emerged around the controversy over The Crew and has gathered over one million signatures across Europe calling for stronger protections against the disappearance of digital games. SKG has worked to bring the issue to EU institutions, including an EU Parliament hearing scheduled in April 2026 focusing on game preservation and consumer rights in digital ecosystems.

    French courts have recently sided with platforms on related, but distinct, issues. In October 2024, the Cour de cassation ruled in favor of Valve in a long-running dispute with UFC-Que Choisir, holding that Valve could prohibit resale of dematerialized games purchased on Steam. That decision effectively endorsed the view that many digital games are licensed, not owned in a traditional property sense.

    The new The Crew case targets a different dimension: not resale, but continued access and the absence of a “best-before” date in consumer-facing information. Where Valve’s case turned on market secondary sales, this dispute focuses on whether a game can be made entirely unusable after purchase without substantial prior warning, refund, or offline alternative.

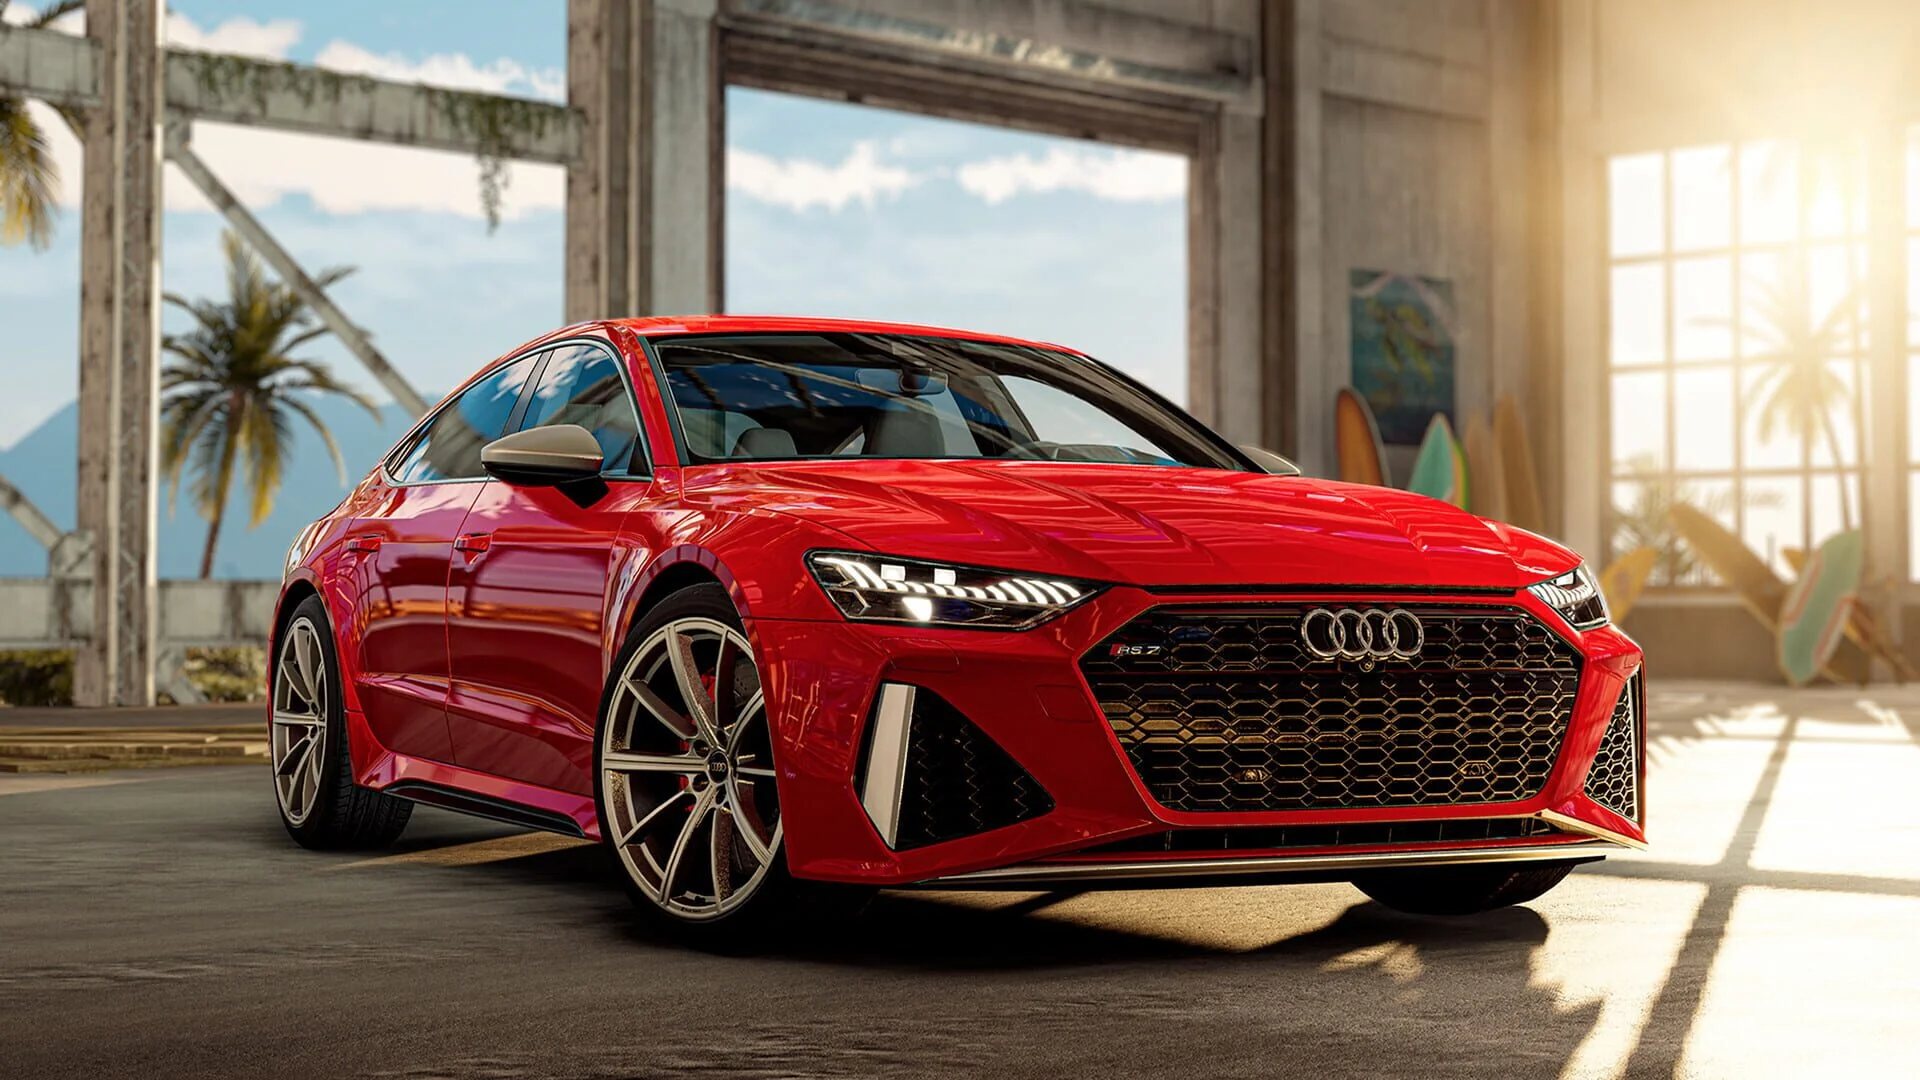
    Screenshot from The Crew Motorfest: Audi Double Car Pack
    Screenshot from The Crew Motorfest: Audi Double Car Pack

    The broader backdrop is a fragmented approach to digital ownership. While most storefronts distribute games under DRM-restricted, revocable licenses, GOG has built a positioning around DRM-free downloads and more durable local access. Any shift in legal expectations in France or the EU may test how sustainable the dominant license-based model remains for heavily server-reliant titles in comparison with DRM-light approaches.

    Operational and economic implications for publishers and platforms

    For Ubisoft, the immediate risk lies in potential court-ordered changes to its standard consumer contracts in France, along with possible damages or restitution mechanisms for The Crew purchasers. More strategically, an adverse ruling could force a re-evaluation of how future online-centric games across PC, PlayStation, and Xbox ecosystems handle end-of-life, especially where even single-player modes require constant server connectivity.

    If courts determine that total loss of use after purchase is incompatible with consumer rights, several operational consequences become plausible:

    • Pressure to maintain minimal “legacy” server infrastructure for older titles, or to ship offline-capable builds before shutdown.
    • Greater legal and reputational exposure for clearly communicating sunset dates, including at the point of sale and on packaging.
    • Heightened scrutiny of wallet and virtual-currency terms when online components are withdrawn.
    • Potential ripple effects on platform-wide policies for content delisting and service discontinuation.

    These shifts could raise long-tail operational costs for always-online and live-service games, particularly for titles with modest but persistent player bases. Publishers relying on aggressive content rotation and catalogue pruning would face a more complex risk calculus around shutting off servers for aging or underperforming products.

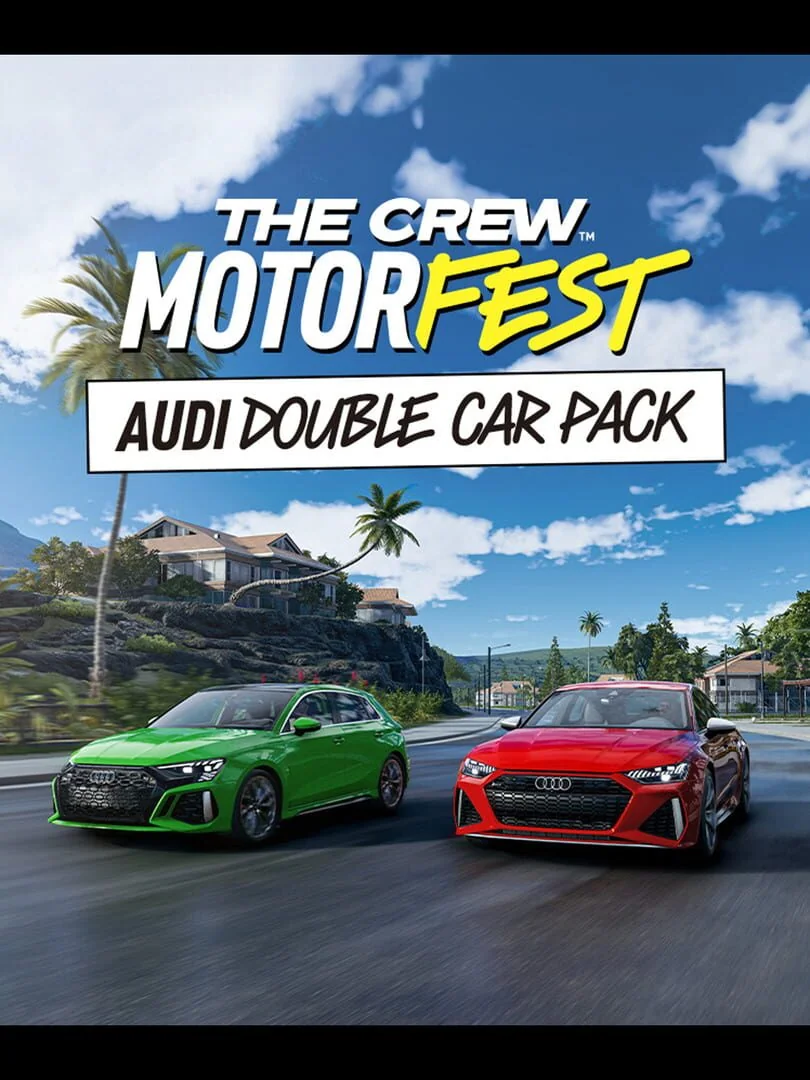
    Cover art for The Crew Motorfest: Audi Double Car Pack
    Cover art for The Crew Motorfest: Audi Double Car Pack

    Conversely, a clear victory for Ubisoft would further entrench the license-based status quo, reinforcing earlier jurisprudence and signaling that, within current EU and French law, publishers retain wide discretion to withdraw server-dependent titles from circulation. That outcome would likely accelerate efforts by advocacy groups to pursue regulatory rather than judicial remedies at the EU level.

    InsightsFinalBoss Signal: Digital access is becoming a regulatory variable

    The UFC-Que Choisir vs. Ubisoft dispute is less about a single racing game and more about where courts draw the line between contractual freedom and the functional disappearance of paid digital goods. As server-dependent design becomes pervasive across PC, PlayStation, and Xbox ecosystems, the economic model for live services is colliding with emerging expectations around durability, transparency, and preservation.

    Whatever the outcome in Créteil, the case elevates “right of use” and shutdown practices from customer-relations questions to hard legal and regulatory variables in Europe. For platforms and publishers, digital ownership is no longer only a messaging or UX topic; it is becoming a structural constraint on how online games are built, sunsetted, and monetized over their full lifecycle.